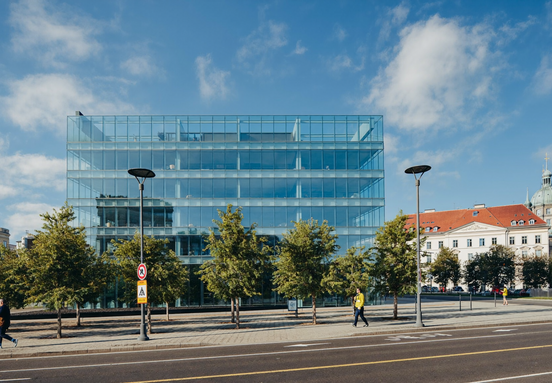
According to Cushman & Wakefield's October 2026 MarketBeat report, Prague's office market remains under intense pressure. The vacancy rate edged down to 5.6% in Q3, leaving just 222,900 m² of available space across the city. For occupiers hunting for office space in the capital, that's good news if you own a building, and a headache if you're looking to lease.
What changed in the quarter
The headline: zero new office completions landed in Q3. Not a single square metre of new supply came to market, marking another quarter of discipline from developers. At the same time, demand from tenants remained steady. Gross take-up reached 107,000 m² in the quarter, showing that businesses are still looking, even as they shop carefully for space that meets their requirements.
The story underneath is the pre-leasing surge. Of the 308,900 m² currently under construction – due for delivery between 2026 and 2028 – about 61% is already spoken for before the building opens. That's roughly 188,000 m² locked in by occupiers hedging against the tight market. It's a rational move in a seller's market, but it means even fewer choices for companies who haven't yet committed.
Rents climb in the city centre
Prime office rents in Prague's city centre broke through the €30 mark in Q3, rising to €32 per m² per month. That's a jump from €30 in the previous quarter, and it reflects a straightforward truth: space is scarce and tenants will pay for quality in the best addresses.
The rent gradient is steep outside the centre. Inner-city locations command €22–€23 per m² per month, whilst outer-city districts stay at €16–€17. If your business can flex to a secondary location, the savings are real. But for companies that need the city-centre postcode – whether for client meetings, talent recruitment or brand presence – the cost of staying put has gone up materially.
Who it hits hardest
Renegotiations now account for over half of all leasing activity. That's occupiers renewing their existing leases rather than companies expanding into new space. These renewals are happening at higher rents because landlords have leverage: if your current lease expires, you can't simply walk away when alternatives are scarce and expensive.
The market is most acute in Prague 1 and Prague 2, where vacancy stands at 3.7% and 1.3% respectively. Conversely, Prague 10 and Prague 3 sit above 11%, offering more room to negotiate – but those districts don't always suit every business type. Brno and Ostrava offer more availability: Brno's vacancy reached 12.7% in H1 2026 with prime rents at €17.50–€18.50 per m² per month, whilst Ostrava sits at 11.4% vacancy and €14–€14.50 per m² per month. Both markets offer breathing room for companies willing to relocate beyond Prague.
What tenants should do now
If your lease renews within the next 12 months, start talking to landlords and brokers today. Waiting until the last three months of your occupancy is a luxury you no longer have. You'll be negotiating from a weakened position when supply is this tight.
Second, reconsider your space needs. Many occupiers are now optimising their existing footprints – taking less space, working smarter, negotiating flex terms – rather than expanding. That trend plays to your advantage if you can make it work. Smaller square metres mean lower absolute rent, even if the rate per m² goes up.
Third, look beyond the city centre if you can. The rent gap between Prague 1 and Prague 4 or Prague 8 is material. If your staff can commute from outer districts or you have no hard requirement to be in the absolute centre, you'll save significantly. Regional markets like Pilsen, Olomouc and Liberec have larger vacancies and meaningfully lower rents if your business model permits it.
Finally, if you're considering a lease term beyond three years, lock in certainty now. Rent reviews every year in this market can be brutal. A longer initial term with step-ups you can forecast is often worth paying a shade more on day one.
What's ahead
Supply will gradually improve. The pipeline of 308,900 m² is substantial, and projects are scheduled through 2028. But delivery cycles can slip, and 61% pre-leasing means much of that new space won't ease the crunch for occupiers outside the pre-lease deals. The Czech National Bank's recent rate environment also supports continued steady demand from businesses in professional services and knowledge industries – sectors that are concentrated in Prague and tend to expand in stable economic conditions.
Watch three things: whether that pre-let percentage falls below 55% (a sign developers believe supply is easing), whether inner-city rents flatten (an early warning that growth is slowing), and whether renegotiation volumes drop below 50% of quarterly take-up (a sign fresh demand is returning). Until then, assume the tight market persists through 2026 and into early 2027.
Key takeaway for your business
This quarter's data tells you three months in advance what's coming: If you have an office lease up for renewal anytime in the next year, move now. Every month you delay costs you money in the end, because you'll be negotiating when landlords hold all the cards. Get ahead of it.
Ready to explore your options? Use our office search tool to find space that fits your budget and location needs across the Czech Republic.
Sources
Cushman & Wakefield Czech Republic Office MarketBeat Q3 2026; CBRE Brno Office Figures H1 2026; CBRE Ostrava Office Figures H1 2026; Knight Frank Regional Office Market H1 2026; Cushman & Wakefield Czech Republic Real Estate Market Outlook 2026.